Market overview of the Metal Embossing Machine Market
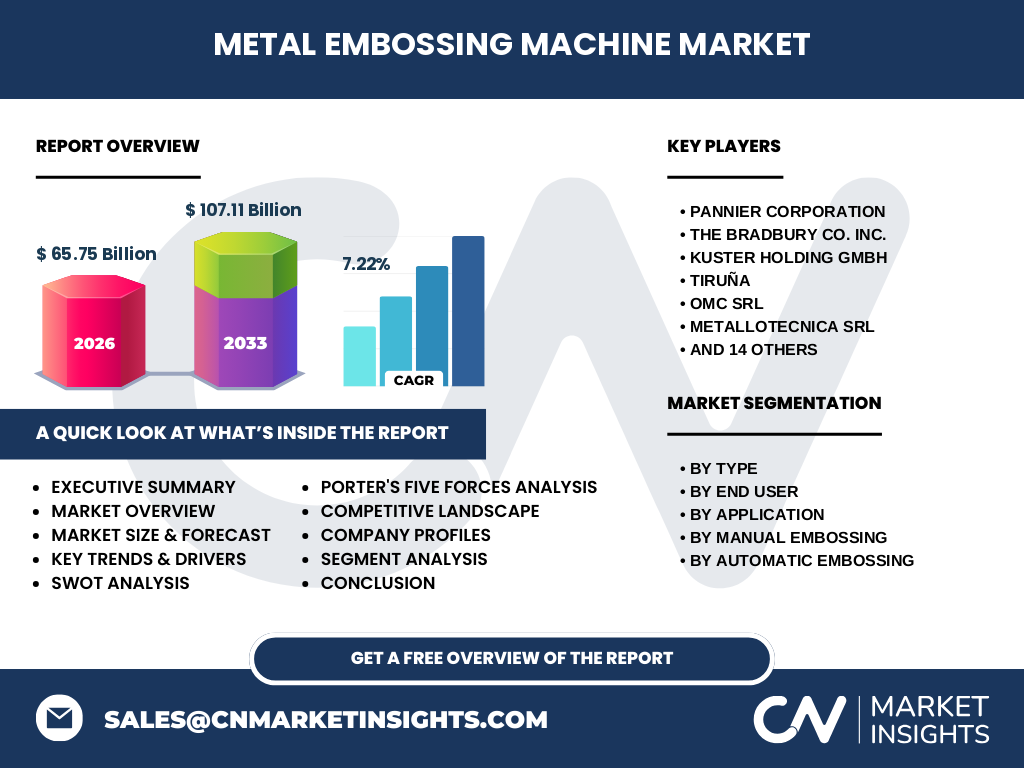
Our analysis indicates the Metal Embossing Machine Market market size stands at 65.75 Billion in 2026. This sector encompasses advanced industrial machinery designed to stamp tactile patterns onto structural metals like stainless steel, aluminum, and copper, heavily serving the Automotive & Transportation Manufacturers and Appliance & Consumer Durables Manufacturers verticals.
Key market drivers, restraints, challenges, and opportunities
Structural growth relies heavily on rising aesthetic and functional demands for patterned architectural panels and vehicle trims. However, high initial capital expenditure for Fully Automatic Embossing Machines presents notable financial constraints for tier-2 suppliers, while supply chain volatility regarding hardened steel rolls challenges continuous equipment manufacturing.
Emerging trends and growth patterns in the Metal Embossing Machine Market
The shift toward automated precision engineering is transforming the Metal Embossing Machine Market industry trends. Operators are rapidly adopting PLC-integrated Semi-Automatic Embossing Machines to minimize material wastage when processing high-grade aluminum coils for luxury home appliances and exterior automotive body panels.
COVID-19 impact analysis and recovery trajectory
Pandemic-era supply chain disruptions temporarily halted production lines across major European and Asian manufacturing hubs. The subsequent recovery trajectory has been robust, fueled by post-lockdown stimulus investments in modern factory automation and rapid retooling for automated sheet-fed operations.
Competitive benchmarking and major market players
Competitive benchmarking reveals a consolidated landscape where established innovators like Pannier Corporation, The Bradbury Co. Inc., and Kuster Holding GmbH dominate through proprietary roll-forming designs. Strategic advantages stem from offering both Sheet-Fed Manual Embossing Machines and automated lines.
Executive summary of key findings
Our comprehensive Metal Embossing Machine Market analysis projects explosive expansion, driven by widespread industrial automation. Key findings highlight that high-speed automated systems capture the largest revenue share, supported by stringent quality standards enforced by ISO and regional machinery directives.
Market forecast from 2027 to 2033
Based on our research, the market is projected to expand from 2027 to 2033, reaching 107.11 Billion by the end of the forecast period at a robust CAGR of 7.22%, reflecting sustained global demand for advanced metal surface texturing.
Segmentation analysis by type, application, and end user
Market segmentation categorizes systems into Manual Embossing and Automatic Embossing. End users span Automotive & Transportation Manufacturers and Appliance & Consumer Durables Manufacturers, applying equipment across Automotive Materials, Home Appliances, and Building Materials.
Regional market analysis and geographic distribution
Geographic performance shows strong concentration in industrialized regions where major ports facilitate heavy machinery export. Asia-Pacific leads volume consumption due to sprawling appliance fabrication plants, while North America and Europe prioritize high-end Tabletop Embossing Machines and specialized automated units.
In-depth regional review of high-growth territories
Regional evaluations underscore rapid industrialization in developing Asian economies, supported by active domestic machinery providers like Nanjing Harsle Machine Tool Co. Ltd. Meanwhile, European markets focus on eco-efficient engineering, driven by established players such as TIRUÑA and OMC Srl.
Company profiles and strategic positioning
Industry leaders maintain distinct strategic positioning. METALLOTECNICA SRL and Holger Clasen GmbH & Co. KG focus on ergonomic handheld and portable solutions, whereas ZIERDT GmbH and Schwer + Kopka GmbH specialize in heavy-duty industrial roll configurations for continuous metal processing.
Porter's Five Forces analysis
Rivalry is intense among established multinational machinery builders, yet high switching costs and specialized technical expertise create a moderate barrier to entry. Buyer power remains balanced against the critical need for customized embossing patterns tailored to exact client specifications.
SWOT analysis of the sector
Strengths lie in high equipment durability and precision engineering. Weaknesses include vulnerability to raw steel price fluctuations. Opportunities abound in emerging EV battery casing texturing, while regulatory compliance standards represent ongoing operational threats.
Value chain analysis from raw materials to end-users
The value chain originates with specialty alloy steel providers supplying forged rolls to OEMs like Yuri Roll Machine Co. Ltd. and The Bradbury Co. Inc. These machines are integrated into Tier-1 manufacturing plants before final deployment in architectural cladding and consumer appliances.
Investment insights and strategic recommendations
High-potential areas include investing in IoT-enabled smart embossing heads that monitor real-time pressure wear. Stakeholders should target partnerships with emerging automotive lightweighting suppliers to secure long-term equipment service contracts.
Conclusion and key takeaways
The trajectory underscores a clear industry migration toward fully automated, high-throughput systems. Capitalizing on the projected growth requires aligning manufacturing capabilities with precision requirements in automotive and building materials sectors.
Research methodology and data triangulation
Baseline estimates are triangulated by combining customs trade registry data, primary stakeholder interviews with engineering directors at firms like Jawo Sheng Precise Machinery Works Co. Ltd., and secondary macroeconomic indicators tracking global manufacturing output.
Scope of the report and coverage parameters
This report covers global revenue estimations, volume shipments, and technological segmentations across manual and automatic machinery categories, excluding custom aftermarket tooling services that fall outside primary OEM fabrication streams.
Recent developments and strategic moves
Recent market activities feature technological alliances and product rollouts by innovators like Botou Yangcheng Cold Forming Machine Co. Ltd. and Anhui LIFU Machinery Technology Co. Ltd., focusing on energy-efficient hydraulic drives and rapid tool-change mechanisms.